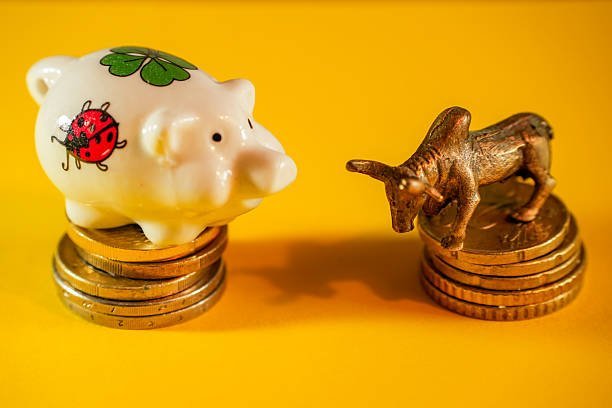
Choosing between a savings accounts and stocks is an important financial decision for European investors. Both options have advantages and disadvantages, and the better choice depends on your financial goals, time horizon, and tolerance for risk. Savings accounts generally provide easier access to money and lower investment risk, while stocks offer greater potential for long-term growth but can fluctuate significantly.
Understanding Savings Accounts
Savings accounts allow people to keep their money with a bank while potentially earning interest. They are generally suitable for money that may be needed in the short or medium term, such as emergency savings, upcoming expenses, or a planned purchase.
The main advantage is stability. Unlike stocks, the balance in a traditional savings account does not normally fall because of daily market movements. However, the interest earned may not always keep pace with inflation.
Understanding Stocks
Stocks represent ownership in companies. Investors can potentially earn returns through rising share prices and dividends.
Stocks can provide stronger long-term growth potential than ordinary savings accounts, but they also carry greater risk. Share prices can fall significantly during market downturns, and investors may lose part of their original investment.
When a Savings Account May Be Better
A savings account can be more appropriate when you need your money soon or want to protect it from market volatility. Emergency funds are usually better kept in easily accessible savings rather than stocks.
Savings can also be useful for short-term goals such as a holiday, car purchase, education expenses, or a house deposit when the money will be needed within a relatively short period.
When Stocks May Be Better
Stocks may be more suitable for investors with a longer time horizon who can tolerate temporary market declines. Long-term investors have more time to recover from market downturns and potentially benefit from economic growth and compounding.
Rather than attempting to predict which individual stocks will perform best, some investors choose diversified funds or ETFs containing many companies.
Consider Inflation
Inflation is an important factor when comparing savings and investments. Even if a savings account earns interest, rising prices can reduce the purchasing power of your money over time.
Stocks can potentially provide higher long-term returns, but those returns are not guaranteed. Investors should consider both potential growth and the risk of losing money.
Think About Your Time Horizon
Your investment time horizon can help determine how much risk you should take.
For money needed within the next few years, keeping a larger portion in cash or savings may provide greater stability. Money intended for long-term goals, such as retirement, may have more opportunity to benefit from investments such as diversified stocks.
Consider Diversification
European investors do not necessarily have to choose between keeping money in savings and investing in stocks. A combination of both can be useful.
For example, an investor may keep an emergency fund in a savings account while investing additional long-term money in a diversified portfolio. The exact balance should depend on income, expenses, financial goals, and risk tolerance.
Check Interest Rates and Investment Costs
Before choosing a savings account, compare the interest rate, account conditions, withdrawal restrictions, and any applicable fees.
For stocks and investment funds, consider brokerage commissions, management fees, taxes, currency-conversion costs, and other charges. Even relatively small fees can reduce long-term returns.
Consider Deposit Protection
European savers should also understand the deposit-protection rules that apply to their bank and country. Eligible deposits in EU banks are generally protected up to €100,000 per depositor per bank under the EU deposit-guarantee framework, subject to the applicable rules.
This protection is different from stock-market investments, where the value of an investment can rise or fall.
Final Thoughts
Savings accounts and stocks serve different financial purposes. Savings accounts can provide stability and easy access to money, making them useful for emergency funds and short-term goals. Stocks offer greater potential for long-term growth but involve market risk.
For many Europeans, the choice does not have to be either savings or stocks. Maintaining sufficient cash savings while investing suitable long-term funds in a diversified portfolio can provide a balanced approach to managing money.
FAQs
Is it safer to keep money in a savings account than stocks?
Generally, savings accounts involve less market risk than stocks. Eligible bank deposits may also benefit from applicable deposit-protection schemes, while stock investments can lose value.
Should I invest my emergency fund in stocks?
Usually, an emergency fund should be kept somewhere accessible and relatively stable rather than invested in volatile assets. This ensures the money is available when an unexpected expense occurs.
Can stocks provide better returns than savings accounts?
Stocks have historically offered greater long-term growth potential than ordinary cash savings, but returns are not guaranteed. Stock prices can fall, and investors can lose money.
Should Europeans use both savings accounts and stocks?
Using both can be a practical strategy. Savings can provide financial stability for emergencies and short-term needs, while diversified investments can potentially support long-term wealth building.